Veterans Day: Wall Street Remains Open 11/11/2026
Market Wrap
Wall Street retreated Tuesday as a hotter-than-expected U.S. inflation report pushed Treasury yields higher and renewed concerns that the Federal Reserve may tighten monetary policy more aggressively. The pullback interrupted Monday's broad market rebound, with technology shares once again under pressure.
The S&P 500 slipped 0.38% to 7,520.93, the Nasdaq Composite fell 0.74% to 25,065.87, and the Dow Jones Industrial Average lost 157.86 points, or 0.30%, to 52,231.89. The Russell 2000 declined 0.68% to 2,821.38.
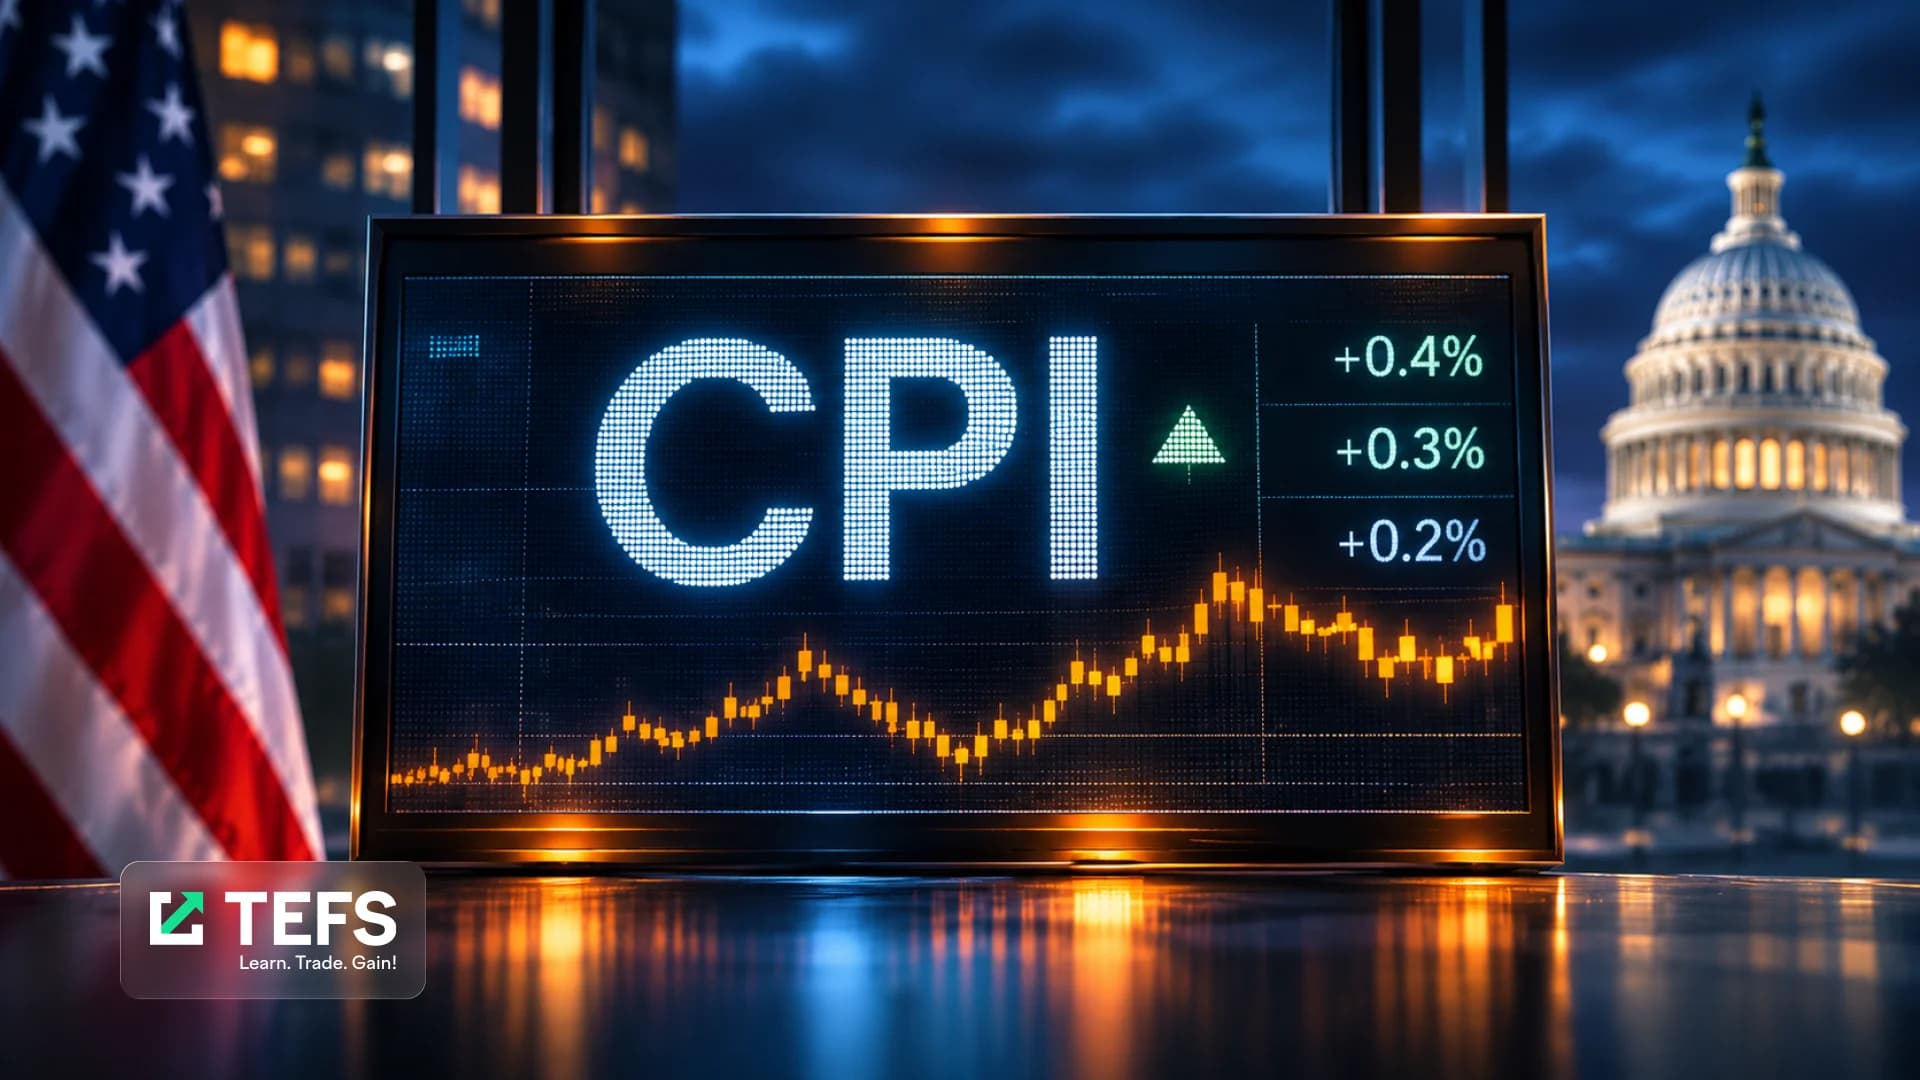
October headline consumer prices increased 0.4% month over month, above the 0.3% consensus estimate. Core CPI rose 0.3%, compared with expectations for a 0.2% increase. The surprise reinforced fears that inflation could remain stubbornly above the Fed's target.
Treasury yields surged in response. The benchmark 10-year yield briefly reached 5%, raising borrowing costs and putting additional pressure on highly valued technology stocks. Investors increasingly considered the possibility of a larger interest-rate increase at the Fed's December meeting.
Nvidia (NVDA) fell about 5.5% as investors continued to assess an investigation involving CEO Jensen Huang. Microsoft (MSFT) also declined, while Broadcom (AVGO) and Amazon (AMZN) held up better, highlighting the uneven response across megacap technology.
Beyond technology, traders remained focused on energy prices and geopolitical developments involving Iran. Although crude has eased from its October highs, lingering inflation risks continue to complicate the outlook for corporate profits and monetary policy.
Wednesday brings Veterans Day, with U.S. stock exchanges operating normally but the Treasury and bond markets closed. Reduced bond-market activity could change trading conditions after Tuesday's sharp move in yields.
The economic calendar is light, with weekly mortgage applications among the limited scheduled releases. Investors will monitor the response to Tuesday's CPI surprise, company earnings and positioning ahead of Thursday's jobless claims and Friday's producer-price report.
Veterans Day Trading: Can Stocks Rally Into Year-End?
U.S. stock markets remain open Wednesday for Veterans Day, even as the bond market closes. The pause in Treasury trading follows a sharp rise in yields on Tuesday, when hotter-than-expected inflation revived concerns about further Federal Reserve rate hikes.
History offers some encouragement for equity investors. Over the past decade, the S&P 500 has posted a median gain of 2.51% between Veterans Day and the end of December, according to Dow Jones Market Data. The outcomes, however, have varied widely from year to year.
The index climbed about 8% over that period in 2023 but fell roughly 8% in 2018. The mixed record is a reminder that seasonal patterns do not guarantee a year-end rally, particularly when inflation and interest rates are moving sharply.
Tuesday's October CPI report showed headline prices rising 0.4% and core prices increasing 0.3% month over month, both above expectations. The 10-year Treasury yield briefly touched 5%, raising questions about how much further the Fed may need to tighten policy.
Higher yields can weigh especially heavily on technology companies by reducing the present value of future earnings and increasing the cost of financing. That matters for AI-focused hyperscalers, which have been borrowing heavily to expand data centers and computing infrastructure.
Oil remains another important variable. Brent crude traded around $91 a barrel Tuesday, well below its October peak near $114, but energy-related inflation pressures and the Iran conflict continue to cloud the outlook.
The S&P 500 is still positive for 2026 despite sharp post-election swings. Whether a traditional year-end advance develops will depend on upcoming inflation data, the Fed's December decision and investors' confidence that earnings can withstand higher rates.
Stocks on the Move
- CoreWeave (CRWV): Shares swung in after-hours trading after third-quarter revenue jumped 168% to $3.66 billion, beating the $3.55 billion consensus. The company also raised its full-year revenue outlook, though AI infrastructure financing concerns persist.
- Mercury Systems (MRCY): Shares slipped nearly 3% after hours despite fiscal first-quarter earnings of $0.52 per share and revenue of $253.2 million, both above the highest analyst estimates.
- Grocery Outlet (GO): Shares dropped 8% following mixed third-quarter results. Revenue of $1.18 billion slightly topped estimates, while adjusted earnings of $0.16 per share matched expectations.
- NextNav (NN): Shares climbed about 8% after hours as third-quarter revenue nearly doubled year over year and its per-share loss narrowed to $0.04 from $0.12. Cash and short-term investments rose to $264.1 million.
- Rigetti Computing (RGTI): Shares fell more than 6% in extended trading after a quarterly loss of $0.08 per share and revenue of $1.4 million missed expectations; full-year revenue guidance also disappointed.
- Firefly Aerospace (FLY): Shares slipped about 2% after hours despite better-than-expected quarterly results. The company narrowed its full-year revenue outlook to $440 million–$450 million.
- Microsoft (MSFT): Shares dropped sharply after Anthropic introduced new Claude workplace tools, including spreadsheets and whiteboards, raising fresh competitive concerns for Microsoft Office.
Watchlist: NVDA, AVGO, CHTR, CRWV, MRNA, FSLR, MSFT, AMZN, AAPL, AMD, MU, FNV, GIB, RGTI, FLY, SPCX
Key Economic Events Today
Economic Data (ET)
- All Day — Veterans Day — U.S. Stock Market Open; Bond Market Closed
Earnings
Before Market Open: CGI Inc. (GIB), ICL Group (ICL), Rumble (RUM)
After Market Close: Franco-Nevada (FNV), Tetra Tech (TTEK), Corteva (CTVA), CAE Inc. (CAE)